October 17, 2026
Dear [Hiring manager's name],
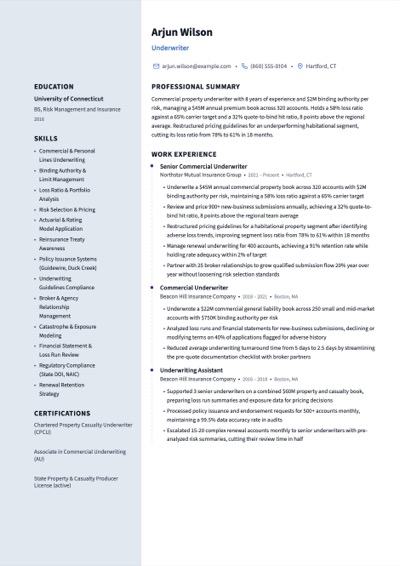
I underwrite a $45 million commercial property book across 320 accounts with $2 million in binding authority per risk, and I hold a 58% loss ratio against a 65% carrier target. I'm applying for the Underwriter role at [Insurance carrier name] because a property book at your scale needs that same discipline between growth and loss ratio, not one at the expense of the other.
My quote-to-bind hit ratio runs at 32%, eight points above my region's average, on 900-plus new-business submissions I review and price each year. When I identified adverse loss trends in a habitational property segment, I restructured the pricing guidelines myself, improving that segment's loss ratio from 78% to 61% within eighteen months without losing the broker relationships tied to it.
I review loss runs and financial statements on every new-business submission, manage renewal underwriting for 400 accounts at a 91% retention rate while holding rate adequacy within 2% of target, and I partner with 25 broker relationships to grow qualified submission flow without loosening risk selection standards. I hold the CPCU designation and an active property and casualty producer license.
I would welcome the opportunity to talk about [Insurance carrier name]'s property growth targets and where a rewritten segment strategy and a strong hit ratio could support them. Thank you for your time and consideration.
Kind regards,
Arjun Wilson, CPCU